When comparing Medicare Advantage vs Medigap, the biggest difference is how your coverage works. Medicare Advantage replaces Original Medicare with an all-in-one private plan that uses a network of doctors and hospitals. Medigap is a supplement that works alongside Original Medicare, so you can see any provider in the country who accepts Medicare. Advantage usually costs less each month, while Medigap usually costs more but offers more freedom and more predictable bills.
For Buffalo seniors, the Medicare Advantage vs Medigap choice matters more than usual this year. Western New York has seen major Medicare Advantage plan and network changes heading into 2027, and the Annual Enrollment Period (AEP) ends December 7.
If you’re still getting familiar with your options, start with our guide on how to compare Medicare plans before open enrollment. Here, we’ll go deeper into the two biggest choices and what they mean for you in Western New York.
How Medicare Advantage and Medigap Work
Medicare Advantage (Part C)
Medicare Advantage plans are offered by private insurance companies approved by Medicare. They cover everything Original Medicare (Parts A and B) covers, and most include Part D prescription drug coverage in the same plan.
Many Advantage plans also add extras like dental, vision, hearing, and fitness benefits. Every plan has a yearly limit on what you pay out of pocket for in-network care. The trade-off is the network: most plans are HMOs or PPOs, so seeing doctors outside the network can cost more or may not be covered at all.
Medigap (Medicare Supplement Insurance)
Medigap plans work alongside Original Medicare. Medicare pays its share first, and your Medigap plan helps pay what’s left, such as deductibles, copays, and coinsurance.
Medigap plans are standardized and labeled with letters, like Plan G or Plan N, so a Plan G offers the same core benefits no matter which company sells it. Medigap doesn’t include drug coverage, so most people pair it with a separate Part D plan. Because there’s no network, you can see any doctor or hospital in the U.S. that accepts Medicare.
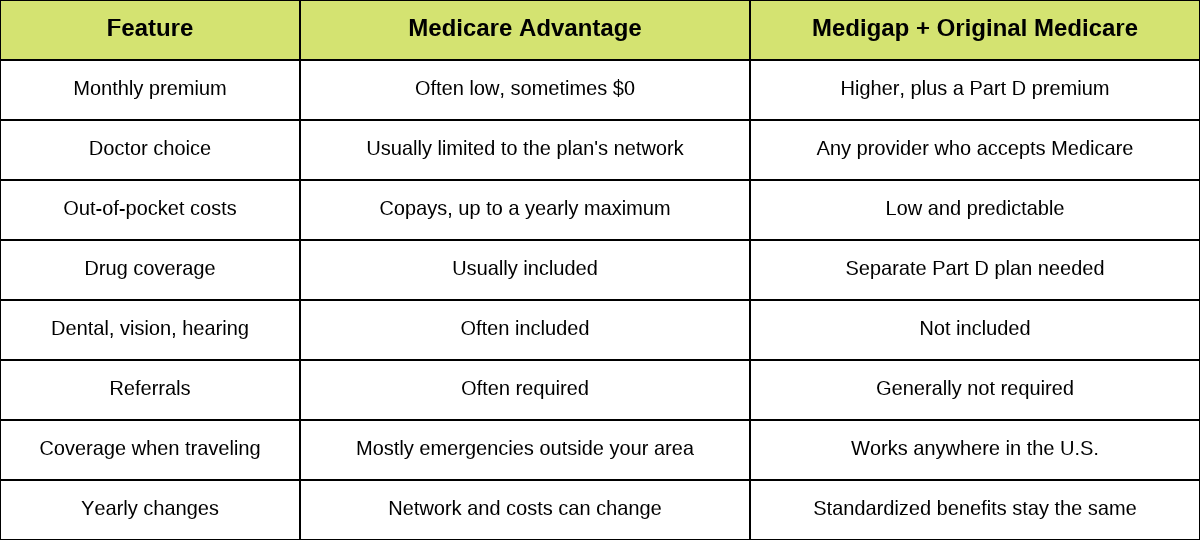
Medicare Advantage vs Medigap at a Glance
Here’s how Medicare Advantage vs Medigap compares on the things Buffalo seniors ask about most.
What’s Different in Western New York for 2027
Western New York relies on Medicare Advantage more than most of the country, so local plan changes affect a lot of people. Over the past two years, many Buffalo-area seniors have received notices that their Advantage plan was ending or that a local hospital or doctor group was leaving their plan’s network.
That trend continues into 2027. Nationally, more than 3 million people with Medicare Advantage need to choose a new plan because theirs is ending. Locally, plans have retired and replaced options, changed premiums, and adjusted which hospitals and specialists are in network.
Before AEP ends, Buffalo seniors in an Advantage plan should:
- Read your Annual Notice of Change (ANOC). It lists every change to your plan’s costs, benefits, and drug list for 2027.
- Check your doctors, hospitals, and specialists. Confirm they’re still in network for 2027, especially any cancer center or specialist you see regularly.
- Check your prescriptions. Make sure your drugs are still covered and see if their tier or cost changed.
- Watch for a discontinuation notice. If your plan is ending, you’ll need to choose new coverage, and you’ll get extra time to do it.
If these changes have you rethinking Medicare Advantage vs Medigap, New York has an important rule that makes switching to Medigap easier than in most states.
New York’s Medigap Rule Gives Buffalo Seniors More Flexibility
In most states, you get one six-month window to buy Medigap without health questions. After that, an insurer can turn you down or charge more because of your health. That makes leaving Medicare Advantage for Medigap risky in many parts of the country.
New York is different. Medigap is guaranteed issue year-round, so insurers must accept you at any time, with no medical underwriting. New York also uses community rating, which means your premium doesn’t change based on your age, gender, or health.
What this means for your Medicare Advantage vs Medigap decision:
- You can move from Medicare Advantage to Medigap later without being denied for health reasons. Keep in mind that Medigap requires Original Medicare, so the timing of a switch depends on your Medicare enrollment periods.
- A 75-year-old pays the same premium as a 65-year-old for the same plan in the same area.
- The trade-off is cost. Because of these protections, Medigap premiums in New York tend to be higher than in most states, though upstate areas like Buffalo generally pay less than downstate.
This flexibility is a big reason Buffalo seniors shouldn’t feel locked in when weighing Medicare Advantage vs Medigap. The right plan this year may not be the right plan five years from now.
Which Option Fits Your Situation?
There’s no single right answer to Medicare Advantage vs Medigap, but these patterns can help you narrow it down.
Medicare Advantage may fit you if:
- You want a lower monthly premium and are comfortable with copays as you use care
- Your doctors and hospitals are in the plan’s 2027 network
- You value extras like dental, vision, and hearing coverage
- You spend most of the year in Western New York
Medigap may fit you if:
- You want to see any doctor or specialist without worrying about networks
- You spend winters in Florida or travel often within the U.S.
- You’d rather pay a higher premium for predictable, low costs when you need care
- You’ve been affected by network changes and want more stability year to year
Still working and covered through your job? Read Medicare vs. employer coverage at 65 before deciding when to enroll.
Key Medicare Deadlines to Know
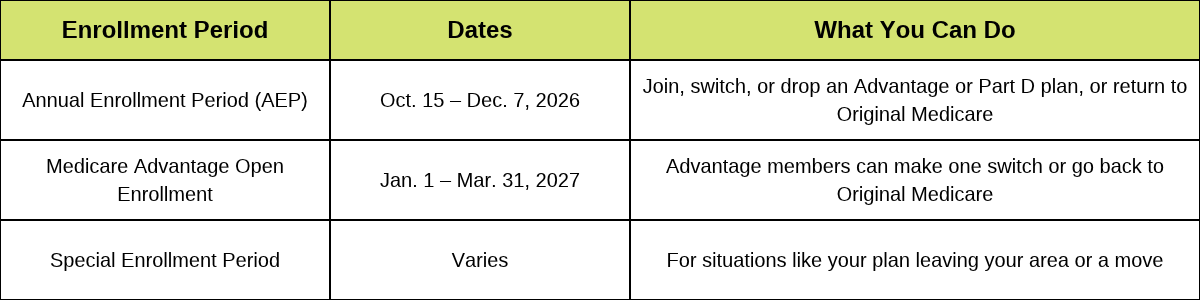
You can compare Medicare Advantage vs Medigap options available in Erie County using the Medicare Plan Finder. New York also offers free, unbiased Medicare counseling through HIICAP at 1-800-701-0501 or aging.ny.gov.
Get Local Help Before December 7
Deciding on Medicare Advantage vs Medigap is easier when someone walks through it with you. Bene-Care’s Buffalo team can review your current coverage, check your doctors and prescriptions, and compare your options for 2027.
Learn more about our Medicare services or call our Buffalo office at (716) 688-8161 to schedule your Medicare review before AEP ends on December 7.


 Recruitment
 Onboarding
 Benefits
 Third-Party Administration
 Time & Attendance
 Payroll
 401K
 HR+
 Business & Commercial Insurance
 Auto/Home/Umbrella
 Health/Dental/Vision
 Medicare
 iSolved
 Umbrella Tech